Saucony grew almost 20 percent in the third quarter while discounting less than a year ago, and accounted for most of the group’s higher revenue forecast. Merrell kept growing through lifestyle doors, while Sweaty Betty’s decline steepened in a tougher UK activewear market.
Saucony is closing the gap on Merrell at Wolverine Worldwide, as the running brand’s third-quarter revenue jumped 19.4 percent to $158.9 million (€143m). Merrell’s lead in quarterly sales narrowed to $19.3 million from $34.2 million a year earlier.
Saucony was again the fastest-growing label at the US footwear and apparel group, which also owns Sweaty Betty. Chief Financial Officer Taryn Miller tied most of the raised full-year revenue forecast to Saucony.
Group revenue rose 7.5 percent to $505.4 million (€454m), its eighth straight quarter of growth. President and CEO Chris Hufnagel called the turnaround “also a growth story.”
| Wolverine Worldwide – Statement of operations | |||
|---|---|---|---|
| 2026 | 2025 | Change | |
| Q3, ended Oct. 3 (USD million) | |||
| Revenue | 505,4 | 470,3 | 7,5% |
| Cost of goods sold* | 229,3 | 247,1 | -7,2% |
| Gross profit | 276,1 | 223,2 | 23,7% |
| Gross margin | 54,6% | 47,5% | +7,1pp |
| Selling, general and administrative expenses | 186,0 | 183,1 | 1,6% |
| Environmental and other related costs (income), net of recoveries | 0,4 | 0,5 | -20,0% |
| Operating expenses | 186,4 | 183,6 | 1,5% |
| Operating expenses as a % of revenue | 36,9% | 39,0% | -2,1pp |
| Operating profit | 89,7 | 39,6 | 126,5% |
| Operating margin | 17,7% | 8,4% | +9,3pp |
| Interest expense, net* | 4,8 | 8,1 | -40,7% |
| Other expense (income), net† | 0,2 | -1,6 | – |
| Total other expenses | 5,0 | 6,5 | -23,1% |
| Earnings before income taxes | 84,7 | 33,1 | 155,9% |
| Income tax expense | 17,6 | 6,8 | 158,8% |
| Effective tax rate | 20,7% | 20,5% | +0,2pp |
| Net earnings | 67,1 | 26,3 | 155,1% |
| Net earnings attributable to noncontrolling interests | 1,3 | 1,2 | 8,3% |
| Net earnings attributable to Wolverine World Wide, Inc. | 65,8 | 25,1 | 162,2% |
| Diluted earnings per share (USD) | 0,78 | 0,30 | 160,0% |
| 9M, ended Oct. 3 (USD million) | |||
| Revenue | 1.469,4 | 1.356,8 | 8,3% |
| Cost of goods sold* | 740,2 | 713,5 | 3,7% |
| Gross profit | 729,2 | 643,3 | 13,4% |
| Gross margin | 49,6% | 47,4% | +2,2pp |
| Selling, general and administrative expenses | 556,1 | 537,5 | 3,5% |
| Environmental and other related costs (income), net of recoveries | 2,2 | 4,5 | -51,1% |
| Operating expenses | 558,3 | 542,0 | 3,0% |
| Operating expenses as a % of revenue | 38,0% | 39,9% | -1,9pp |
| Operating profit | 170,9 | 101,3 | 68,7% |
| Operating margin | 11,6% | 7,5% | +4,1pp |
| Interest expense, net* | 18,4 | 24,6 | -25,2% |
| Other expense (income), net† | -0,6 | -4,5 | -86,7% |
| Total other expenses | 17,8 | 20,1 | -11,4% |
| Earnings before income taxes | 153,1 | 81,2 | 88,5% |
| Income tax expense | 30,7 | 12,7 | 141,7% |
| Effective tax rate | 20,0% | 15,6% | +4,4pp |
| Net earnings | 122,4 | 68,5 | 78,7% |
| Net earnings attributable to noncontrolling interests | 5,2 | 4,5 | 15,6% |
| Net earnings attributable to Wolverine World Wide, Inc. | 117,2 | 64,0 | 83,1% |
| Diluted earnings per share (USD) | 1,40 | 0,76 | 84,2% |
| The 2025 periods ended Sept. 27, 2025. | |||
| *In both 2026 periods, IEEPA tariff refunds received in Q3 reduce cost of goods sold by $32.6 million and interest expense by $1.3 million. | |||
| †A minus sign marks net other income. | |||
| Source: Wolverine Worldwide | |||
A tariff refund inflates the margins
The headline profit figures need a footnote. Wolverine received $35.3 million (€32m) in refunds of tariffs it had paid under the IEEPA, which added about 640 basis points to both gross and adjusted operating margin.
Gross margin reached 54.6 percent. Without the refunds it was 48.2 percent, a gain of 70 basis points, as price increases, more full-price selling and supply chain savings outweighed roughly 170 basis points of unmitigated tariff costs.
The underlying business still improved. Adjusted operating margin excluding the refunds rose 230 basis points to 11.4 percent, and net debt fell 26.4 percent to $399 million (€359m), with nothing drawn on the revolving credit line at quarter end.
Saucony sells more while discounting less
Saucony’s wholesale and DTC sales both grew by double digits, according to Miller. Saucony.com posted mid-teens growth, its best quarter in 2026, and wholesale outside the US grew faster than at home.
Hufnagel said Saucony ran fewer promotions than a year earlier, even as discounting increased across the US running category. The Endorphin Azura ranked among the three best-selling styles on the group’s global DTC channels and remains on course to be the largest franchise launch in Saucony’s history, while the new Endorphin Speed 6 quickly became one of the best sellers on saucony.com
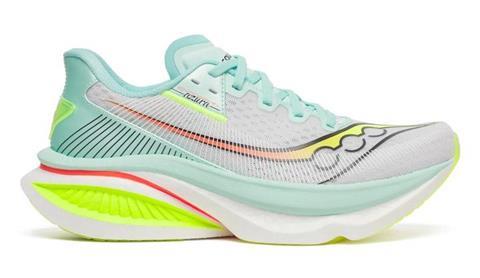
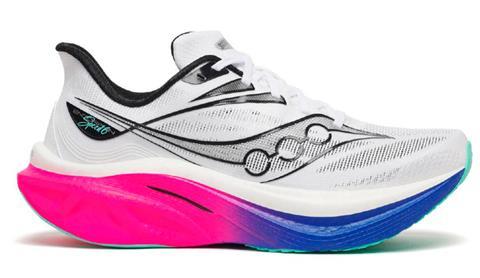
Europe is where the lifestyle side grows fastest. EMEA (Europe, Middle East and Africa) wholesale and DTC led lifestyle growth, which management connects to its Key City program in London, Paris and Berlin: the race sponsorships, store presence and community events described in Saucony’s marketing playbook. In London, Saucony again backed the London 10K and the Shoreditch Half Marathon this quarter.
Next year the program travels to the US and Asia Pacific, and Saucony plans another Endorphin super shoe, the Endorphin Zenith. Hufnagel also named sporting goods retail as a channel where the brand is underpenetrated. Wolverine kept its 2026 forecast of growth in the mid teens, which on last year’s $533.1 million would lift Saucony above $600 million (€539m) for the first time (SGIE calculation).
Merrell looks beyond the trail
Merrell, the group’s largest brand, grew 6.5 percent to $178.2 million (€160m), its ninth straight quarter of growth. Growth was spread evenly between wholesale and DTC, and between the US and international markets, and Merrell’s own DTC sales improved to mid-single-digit growth from a weaker first half.
The lifestyle business is where Wolverine wants a bigger share. Merrell now sells through fashion boutiques and specialty stores that did not stock it before, which the company calls Tier 0 to Tier 2 accounts, and the classic Moab is selling more to women. A Harris Tweed collaboration on the Chameleon and Jungle Moc styles ran this quarter, alongside “Outside in the City” events in London, New York, Taipei and Sydney, among others.
Fourth-quarter growth will slow. Hufnagel cited international shipments moving into the first quarter, a model changeover and the comparison with last year’s 53-week fiscal year. Wolverine still expects Merrell to grow by a mid-single-digit percentage in constant currency in 2026.
Visualizza questo post su Instagram
Sweaty Betty slips further in the UK
Sweaty Betty’s revenue fell 7.0 percent to $41.4 million (€37m), or 6.5 percent in constant currency. That is a steeper decline than in the first and second quarters, when currency-adjusted sales fell 4.4 percent and 2.7 percent.
About half of the fall comes from resetting the US business. In the UK, a more promotional women’s activewear market hurt online sales, while the brand’s own stores grew by a low-single-digit percentage. Excluding the US, revenue was down 3 percent.
The bright spots are small. International wholesale grew by double digits, and Asia Pacific revenue more than quadrupled from a low base after a new store opened in Shanghai, with more doors in China planned before year end. Wolverine still forecasts a low-single-digit decline for the full year.
The brand’s next visible step involves Saucony. Hufnagel confirmed a Saucony-branded apparel capsule designed together with Sweaty Betty’s team for the first half of 2027, sold mainly through DTC at first.
What’s next
Wolverine raised its 2026 forecast to revenue of $2.00 billion to $2.01 billion (€1.80bn). Fourth-quarter sales at the Active Group, home to all three brands, should rise by a mid-single-digit percentage.
The leaders of those brands have reported directly to Hufnagel since September, when Wolverine eliminated the Active Group president role. Saucony’s marketing is in the hands of CMO Wendy Kula, hired from Nike in May.