Textile-to-textile recycling is still far from being implemented on an industrial scale. What role can brands play in changing this?
With more than 20 years of experience in the apparel, footwear, and fashion industries -including leadership roles at Adidas, Nike, H&M, and McKinsey - Evan Wiener knows firsthand the impact brands can have on driving change. As a Senior Advisor at ReHubs, the European industry initiative dedicated to promoting textile recycling, he is now working on the strategic and economic framework needed to scale textile-to-textile recycling to an industrial level. Despite numerous successful pilot projects, textile recycling is still far from reaching industrial scale.
In this interview, Wiener explains what brands can do to advance the circular economy beyond pilot projects. He also addresses one of the industry’s biggest challenges: How can brands help close the gap between supply and demand that prevents textile-to-textile recycling from becoming economically viable on a large scale?
Mr. Wiener, many brands have ambitious circularity targets, yet textile-to-textile recycling remains largely at pilot stage. What is preventing the industry from scaling?
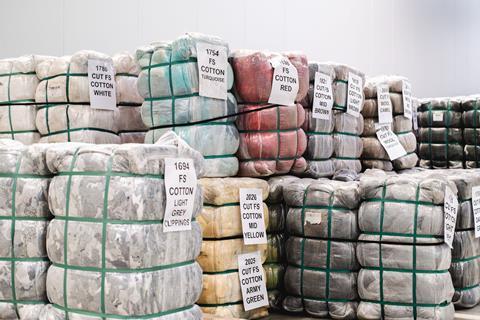
Evan Wiener: The honest answer is that the economics don’t yet work at scale, and that’s true across the full value chain. The industry is caught in a supply-demand deadlock: brands need confidence that recycled fibres will be available at the right quality, volume and cost before making major purchasing commitments, while recyclers need long-term demand before they can justify investing in industrial-scale capacity.
Recycled materials can still cost two to three times more than virgin equivalents, depending on the fibre and process. At the same time, the infrastructure investment required is substantial. In ReHubs’ recent report with BCG, Advancing Textile Circularity, we estimate that reaching the tipping point for a viable European system - roughly 2.7 million tonnes of textile-to-textile recycling per year by 2035 - will require €8 to 11 billion in capital investment, plus €5 to 6.5 billion in recurring annual operating costs.
No single brand or actor in the value chain can carry that alone. We need demand from brands, investment, effective EPR schemes, public support to de-risk first-of-a-kind infrastructure and, ultimately, a more efficient system across the entire value chain.
What can brands do today to help build that system - from collection and sorting to creating demand for recycled fibres?
Brands have several important levers. First, they can reduce the amount of product that becomes waste in the first place, particularly overstock and unsellable inventory. Because of the industry’s production model and the difficulty of predicting seasonal demand and trends, brands often produce 10 to 40% more than they can sell.
Second, products need to be designed for reuse, repair, disassembly, traceability and recyclability. That helps enormously on the sorting and processing side. The purer and more consistent the feedstock, the better the recycling output.
Third, brands need to create real demand for recycled materials. The industry needs to move beyond pilots and one-off offtake commitments towards long-term purchase agreements that give recyclers and investors something bankable. In my view, the ambition should be for the majority of a brand’s materials portfolio to consist of recycled and other low-impact materials.
Finally, brands can support the development of EPR systems and the Producer Responsibility Organizations (PROs) that will help fund collection, sorting and recycling infrastructure, while also educating consumers about reuse, repair and appropriate collection.
Textile-to-textile is far better than bottle-to-textile
Textile-to-textile recycling is still considerably more expensive than established routes such as bottle-to-textile. How should brands and the wider industry address that cost gap – and who should pay?
Textile-to-textile is far better from a circularity standpoint than bottle-to-textile. Bottle-to-fiber pulls PET out of a closed bottle-to-bottle loop and turns it into a one-way trip, since fiber is rarely recycled again.
We should not build the transition around the assumption that brands will simply absorb the premium. Textile-to-textile recycled fibres are a new material category with structurally higher processing costs than established alternatives, so the rules of the game have to change if we want to reach industrial scale.
No single actor should absorb the entire cost. Producers will carry greater responsibility through EPR. Brands need to create demand. Public funding can help de-risk first-of-a-kind infrastructure, while private investors ultimately need to finance scalable commercial assets. The entire value chain also needs to become more efficient as volumes grow.
We need mechanisms such as long-term demand agreements, eco-modulated EPR fees, recycled-content requirements where appropriate, and public-private de-risking. The goal should be to make textile-to-textile materials affordable and investable over the long term rather than assuming immediate price parity with virgin or bottle-derived alternatives.
Sports brands are particularly well positioned to lead on demand because sportswear is one of the most polyester-dominant categories in apparel.
Design needs to have circularity in mind
You mentioned Polyester. How important are product design and material choices for making textile-to-textile recycling work in sportswear, where blends, coatings and membranes are common?
Products are far too linear today. They need to be designed with circularity in mind - for reuse, repair, disassembly, traceability and recyclability - and we need clear design standards that the industry can use consistently.
Chemical recycling can help address the reality of blended materials in sportswear. But the purer the material, the better the output, so we should still aim to provide recyclers with high-quality, consistent feedstock wherever possible.
The industry is beginning to move in this direction. For example, Arc’teryx, part of Amer Sports, has announced new design standards through its System 0 platform. The key question is how quickly this kind of design infrastructure can scale across growing businesses and ultimately across the wider industry.
EPR is needed for successful implementation
Beyond individual brand initiatives, what needs to happen in terms of standards, financing and regulation to make circularity commercially viable?
We need a unified and coordinated approach across the value chain, and this is exactly what we are doing at ReHubs. The industry still lacks sufficient shared standards for feedstock, quality, terminology, traceability, mass balance, recyclability and acceptance of recycled outputs.
At the same time, the financing model needs to combine private investment, public de-risking, reliable brand demand and well-designed EPR. Investment cannot focus only on recycling plants: collection, sorting and preprocessing infrastructure also need to scale, because there is no recycling industry without reliable, lower-cost feedstock. Ultimately, voluntary leadership alone will not be enough given the current cost differential. What I believe will start to move the system is demand aggregation through policy. Voluntary leadership alone will not get us there given the higher costs. We see this in other industries, like agriculture, that continue to struggle to scale low-impact solutions without legislation taxing the status quo or making the more sustainable option less expensive. That’s why fashion and textiles are stuck in this supply-demand deadlock.
EPR is particularly important because it makes brands and producers financially responsible for the waste they generate and can direct funding towards the infrastructure required to process it.
That is also why ReHubs exists. No single recycler, brand, PRO, sorter, investor or policymaker can solve the system alone. Our role is to bring these actors together around concrete industrial projects and help create the conditions for investment and scale.
If you could tell a sports brand to start tomorrow with three concrete measures to accelerate circularity, what would they be?
It’s easy to say what needs to happen. It’s much harder to say what can actually be implemented within businesses that are built around consistency, seasonal cycles and quarterly financial targets. But we now have a much clearer picture of what needs to change. My three priorities would be:
- First, buy and use more recycled materials. The majority of a brand’s total materials portfolio should ultimately be recycled and other low-impact materials. That is essential to creating the demand needed to scale recycling.
- Second, design products for circularity. Brands should build reuse, repair, disassembly, traceability and recyclability into product development and help create common design standards.
- Third, accept responsibility for textile waste. Brands should support effective EPR systems and help shape the legislation, standards and PRO mechanisms that ensure funding reaches the infrastructure needed to collect, sort and recycle textiles.
The transition will not be achieved by any one measure. It requires the entire value chain to move together. ReHubs is bringing those players together, and our door is always open to any brand or organisation that wants to join us in building textile circularity at industrial scale.