Nike has more customer data than ever and just left the S&P 100. Lululemon has lost 83 percent of its value in under three years. Neither stopped collecting data. Both stopped knowing. Sebastien Willefert’s three-part Playbook series starts this week.
On 21 Sept., Nike left the S&P 100 after almost eighteen years. The social media feed has already decided what this means: Some are writing obituaries for the Air Jordans of their childhood; others are running autopsies on the direct-to-consumer strategy.
All are asking how Nike dropped off the S&P 100. I think that actually is the second-best question. The better one is
“Who decided a footwear company belonged in the S&P 100, and what did the market think it was buying?”
How Nike became worth less than it was worth in 2008
Nike joined the S&P 100 in Dec. 2008, at the depths of the financial crisis, in the months when the index was shedding banks that had failed or been swallowed. It arrived with a market value of about $25 billion (€22bn).
At its Dec. 2021 peak, when the world was trying to find a way out of Covid-19 and the search for wellness and e-commerce were at their summit, Nike was worth about $264 billion (€233bn) on net income of $5.7 billion (€5bn). That is a forty-six times earnings-to-revenue, for a company that sells shoes.
Now compare adidas in the same quarter. Same industry, same category, same customers. Nike traded at roughly 5.9 times revenue adidas traded at roughly 2.3. In 2026, Nike sits at about 1.2 times revenue. adidas sits at about 1.2 times revenue. They have converged exactly.
The comparison between two footwear giants disposes of an easy explanation. The premium was not that sportswear was expensive in 2021, because adidas was in the same sportswear category and was not expensive. The gap belonged to Nike alone, and it is now entirely gone.
Nike is worth between an estimated $54–$57 billion (€48– $50bn) today, roughly 2.2 times its 2008 value. Meanwhile revenue has grown 2.5 times, from $18.6 billion (€16.4bn) to $46.4 billion (€40.9bn) for the FY 2025/26, and net income only 1.6 times, from $1.9 billion (€1.7bn) to $3.1 billion (€2.7bn).
What do these numbers show? The business got bigger faster than the company got more valuable.
Nike now trades at a lower multiple of its sales than it did in Dec. 2008, in the depths of the worst financial crisis in eighty years.
So what was in the gap?
The mirror Nike built for itself
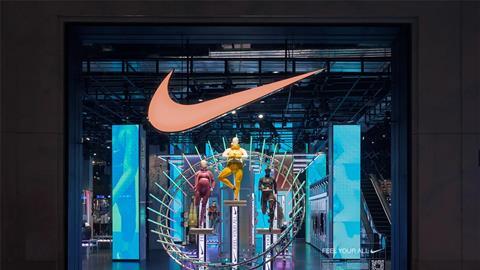
Nike’s Consumer Direct Offense was launched in 2017 under Mark Parker and accelerated through the pandemic. Its modus operandi? Bring the customer inside.
Cut the wholesale partners, own the checkout, own the data, own the customer.
And “own the data, own the customer” was not a metaphor. Nike bought Celect, a predictive analytics company, in 2019 and Datalogue, a data integration company, in 2021. John Donahoe told investors that the strategy started with digital, that the acquisitions would put the right product in the right place at the right time, and that Nike was only scratching the surface of personalization.
By the end of fiscal 2021, direct digital was tracking towards 21.5 percent of the business and the SNKRS app alone was worth a billion dollars a year.
A footwear company bought data companies, told the market it was becoming a personalization business, and was paid a personalization multiple. Lockdown looked like proof; the strategy was a lock-in. By 2021, Nike knew more about its customers than it ever had. What it built, though, was a company that measured itself against itself, on its own shelves, in a market where competitors were growing faster than it was.
A multi-brand retailer is a comparison engine. Your own store is a mirror.
A luxury Maison does not ask. Hermès runs no referendum on the next Birkin. The house holds a position, commits to it, and lets desire arrive afterwards. Authority in that world comes from conviction plus the craft to deliver it.
Nike did the opposite, and the result was a business with more information about its customers than at any point in its history and less conviction about what to put in front of them.
Half deterioration, half a broken promise
Five years on in 2026, Nike’s revenue is $46.4 billion (€40.9bn), slightly higher than at the peak. Net income is $3.1 billion (€2.7bn), roughly half. Gross margin is down 190 basis points. Market value is around $54 billion (€48bn).
So the 78 percent fall in stock price from its 2021 peak is not one thing, it is two things multiplying. Earnings halved, and the multiple went from 46x to 18x.
Roughly half the collapse is the business genuinely deteriorating, and roughly the other half is the market declining to keep paying a technology price for a sneaker.
Only one of those halves is a management failure. The other was a promise that was never going to be delivered.
What Nike got wrong about knowing its customer
Nike had the right ambition and the wrong instrument. Wanting to know your customer better is not a mistake. Believing that owning the checkout would deliver it was.
Nike had two instruments for knowing what people wanted: Wholesale buyers, who could tell you what a particular city would take next season; and run clubs, where you stand in a car park at seven in the morning with the people who actually use the product. It cut the buyers and bought the analytics companies. It kept the app and stepped back from the clubs. In both cases, it chose the version of a relationship that produces data over the version that produces knowledge.
On and Hoka did the opposite. Both grew through running specialty wholesale, where somebody watches you run and fits the shoe. Both invested in physical running clubs in the same window Nike was stepping away from them. They are now roughly two-billion-dollar brands taking share, built on the instrument Nike put down.
The stock market never found a way to price those relationships. There is no technology multiple for a conversation in a car park. Nike Direct was $16.4 billion (€14.5bn) in 2021. It is $17.7 billion (€15.6bn) today.
Five years, a war on its own wholesale partners, real damage to the brand’s presence in the stores that built it; all for eight per cent growth. Nike Direct is now shrinking six per cent a year while wholesale grows six.
The partners Nike spent half a decade cutting are the ones currently holding the company up.
What replaced Nike in the S&P 100
Nike was not the only name to leave the S&P 100 this month. Honeywell Aerospace, Simon Property Group and Colgate-Palmolive went with it. In came Dell, Palo Alto Networks, Arista Networks and SanDisk. A brand, an aerospace business, a mall landlord and a toothpaste company, replaced by servers, storage, networking and security.
That reshuffle deserves more attention than Nike’s individual failure.
The S&P 100 is not a scoreboard. It is a ledger of a society and a look into its future.
For almost eighteen years that ledger included a company whose product was self-image. Nike arrived as the banks were leaving. It leaves as the infrastructure arrives, replaced by the platforms on which the next Nike will be built.
The analysts agree on more than they think
The most serious bear case on Nike belongs to Bank of America. Analyst Lorraine Hutchinson cut Nike to Underperform on 25 Sep, took the target to $30 from $47, and moved her recovery expectation from spring 2027 to fiscal 2028. Her fiscal 2027 earnings estimate of $1.43 implies a dividend payout ratio around 107 percent, which is the one genuinely uncomfortable number in this debate. It asks whether Nike can keep returning capital while it waits for product to work. Oppenheimer, the same week, trimmed to $52 and kept Outperform, citing early improvement in collaborations and basketball. Recovery, in its reading, is already visible in the product.
Look at what those two notes actually disagree about: Not whether Nike recovers. When.
The bull and the bear are arguing about the calendar, which means they agree on the one thing neither of them examines: That the brand underneath is still capable of recovering at all.
That is the part worth examining.
Where the desire went
This month I was scrolling a flash-sale site and there was the Nike Dunk Low Panda at half price.
StockX ranks the Panda as the most resold sneaker in its history, ahead of even the white Air Force 1. It retailed at $100 (€88) and traded at three times that. Today it sits next to end-of-season stock, at a fraction of what it fetched in 2021. The desire is gone.
Desire instruments drive people’s behavior: From plunging into the archives for much-loved franchise products to limiting access to those precious memories to make them ever more special. Nike’s problem was never a shortage of desire instruments. Under Donahoe it worked them harder than ever: Dunk and Air Force 1 retros in overdrive, SNKRS turning scarcity into a weekly event.
But archive and scarcity are extractive instruments. They harvest desire, they do not create it, and each one fails in a signature way when it runs alone. Overdo the archive and the icons flatten, which is what happened to the Dunk and is happening now to adidas as it discounts the Samba that rescued it from the Yeezy hole. Overdo scarcity and you build a market for bots and resellers, in which the brand captures almost none of the value it manufactured.
What Nike knows how to do that no one else can buy
Now consider a third instrument: craft. The ability to surprise, by making a singular object and telling the world why it exists. Unlike data and an archive, craft creates desire rather than harvesting it. And Nike stopped feeding it. An archive is only a balance sheet of past innovation, and Nike spent five years drawing down the vault without depositing.
Every one of Nike’s icons started as an athlete’s problem, clearly solved and explained to the world, from the Waffle Trainer to the Air Max and the 2020 Alphafly. The habit is not extinct. It produced the Vaporfly in 2017, resetting what a marathon shoe could be, and rewriting the rule and record book. That was nine years ago, not fifty-five.
Now look across the street at another cultural icon. The adidas Samba was a 1949 indoor football boot that became a fashion object seventy years later, through terrace culture and then TikTok. The All Star and the Stan Smith were adopted by culture rather than engineered for performance.
Nike’s archive was built, one athlete’s problem at a time. adidas cannot decide to have another Samba. Nike can decide to solve another athlete’s problem.
Nike will survive. The question is what kind of company survives.
Don’t worry, Nike will be fine. It has $46 billion of revenue, a wholesale channel back in growth, and a Chief Executive who came out of retirement to run it. But the road back is not a channel strategy.
You can know everything about a customer and still not know what they want. Nike ended up with all the data and none of the desire.
Every brand in this industry has an archive, and every brand can stage a drop. What none of them can buy is fifty years of practice at making something an athlete actually needed. Nike still has it. And it has just hired someone who has done it three times.
Nike now knows where the dial sits; the setting between archive and scarcity, product and distribution, the consumer and the retailer. It has tried, it has failed, and it has learned where both limits are.
The next great brand will not be the one that owns the most stores or the most data. It will be the one people would actually miss.
The Playbook is an independent column. The views expressed are the author’s own.
The Playbook with Sebastien Willefert
Strategic thinking for the sporting goods industry
An operator’s perspective on the industry’s most pressing strategic questions. Sebastien Willefert distills two decades of brand, commercial and marketing leadership into digestible, actionable insights. From growth strategy to community leverage, The Playbook translates experience into answers.